Capital should buy a specific next step, not validate an idea. Before drafting a deck or taking on debt, founders must ask: what precise risk is this money meant to de-risk—prototyping, inventory, compliance, sales capacity, or runway? The best startup funding options depend on that answer, repayment ability and how much ownership or control you will trade. A large cheque may accelerate growth, but can also add costly obligations.
UK market context reinforces the need to compare: the British Business Bank’s 2026 report says 2025 equity finance fell to 2019 levels, while lender choice broadened and flexible finance was used more for cash flow; about half of smaller businesses sought external finance. Equity remains one route; match startup funding options to need, not headlines.
Start with the next proof point
Pick a proof point that reduces risk: 20 paying customers, repeat orders, a working prototype, approval, or signed distribution. Estimate its cost: net monthly burn × months + one-offs + buffer – cash and committed revenue. Record assumptions; do not copy another startup’s round size.
Illustration, not a customer case: A food producer needs £18,000 for a production run, has £27,000 in confirmed orders, but buyers pay after delivery. That is a timing gap, not automatically a case for venture capital for startups. Ask for customer deposits or supplier terms, compare a short-term loan, and model a two-month delay. Verify buyer credit, cancellation terms and margin before borrowing against orders.
Match the money to the job
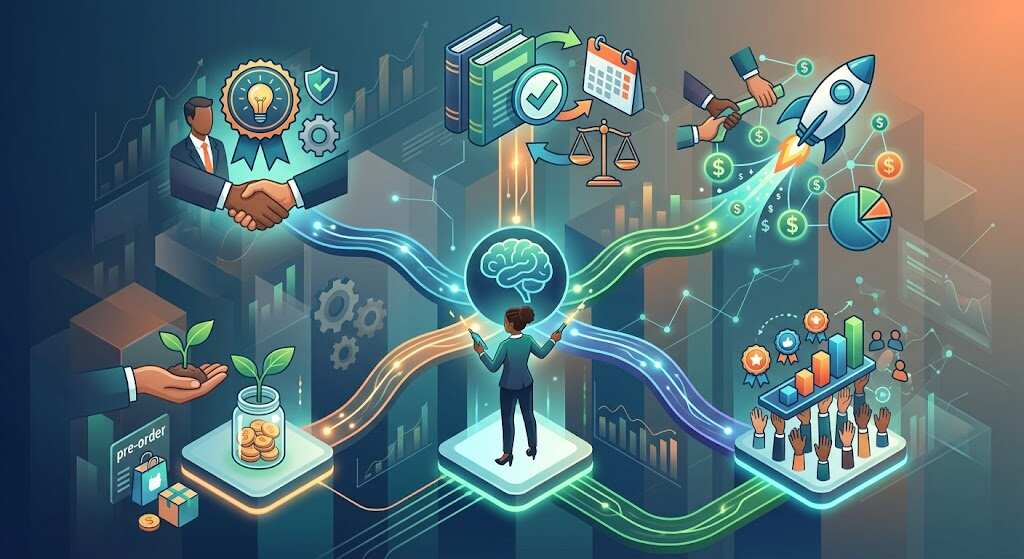
Bootstrapping, pre-sales and customer deposits protect ownership and test demand, but may slow growth. While small business grants provide ideal non-dilutive funding for eligible R&D, they demand strict discipline: review active Innovate UK guidelines carefully, and never budget around funds you haven’t secured.
Debt avoids dilution but must be repaid if sales disappoint. UK startup loans can fit a defined need; angel seed funding can finance a longer path to recurring revenue. Venture capital for startups buys speed and networks in large markets, in exchange for ownership and influence. Crowdfunding can add customers but requires a campaign, disclosure and fulfillment. Compare startup funding options by cost, timing, control and downside.
In the UK, the government-backed Start Up Loan offers £500–£25,000 at fixed 7.5%, repayable over one to five years. It is a personal loan for business use, not a grant: the founder is personally responsible. Elsewhere, check local terms.
Learn from a founder case—carefully
Quarter founders Fabian Clark and Rohan Radhakrishnan say they borrowed £10,000 in 2022 to meet rising orders for Quarter Gin and then expanded the range. This Start Up Loans programme case is illustrative, not typical: the useful lesson is to link a defined sum to visible demand and a specific operating step.
Make your case fundable
Match the application to the capital: lenders test repayment, investors test scale, and grant panels test eligibility. Prepare a 12–24-month, driver-led forecast with use of funds, runway, sales assumptions, gross margin, cash conversion, next milestone and downside case. Include bank statements, orders, retention, cap table and founder roles. For seed funding, show that capital—not unresolved product learning—is the constraint.
For a startup business loan, compare total repayment, fees, variable rates, collateral and personal guarantees. For equity, assess dilution, investor rights, board controls and liquidation preferences—not valuation alone. Start Up Loan applicants need a business plan and cash-flow forecast.
Also Read: Ethereum Price Prediction October 2026: BitMine Reaches 5.98M ETH as Analysts Target $6,000
Conclusion: Choose money the business can live with
Funding is not a trophy. Choose the least costly capital that reaches the next verifiable milestone without making the downside unlivable. Use non-dilutive funding from small business grants or customer revenue when it fits, debt when cash flow can service it, and equity when the market rewards speed and the company can absorb dilution. Good startup funding options buy proof, capacity or time; know which before signing.
FAQs
1. What are the best startup funding options for a new business?
The best startup funding options vary: use customer revenue where possible, small business grants for eligible R&D, debt for predictable repayment, and seed funding only when its dilution makes sense.
2. How much should I raise?
Raise enough to reach a defined milestone, plus a realistic buffer, less current cash and committed revenue. Model slower sales before setting the amount.
3. Is a UK Start Up Loan a grant?
No. It is personal borrowing for business use; current terms are £500–£25,000 at a fixed 7.5% over one to five years.
4. Can I get non-dilutive funding?
Yes. Pre-sales, eligible grants and some revenue-based finance avoid selling shares, but carry delivery duties or repayment. Verify terms first.
5. When should I seek venture capital?
When the market rewards fast expansion, demand is evidenced, and capital—not unclear positioning—is the main constraint. Venture capital is a strategy, not a badge
